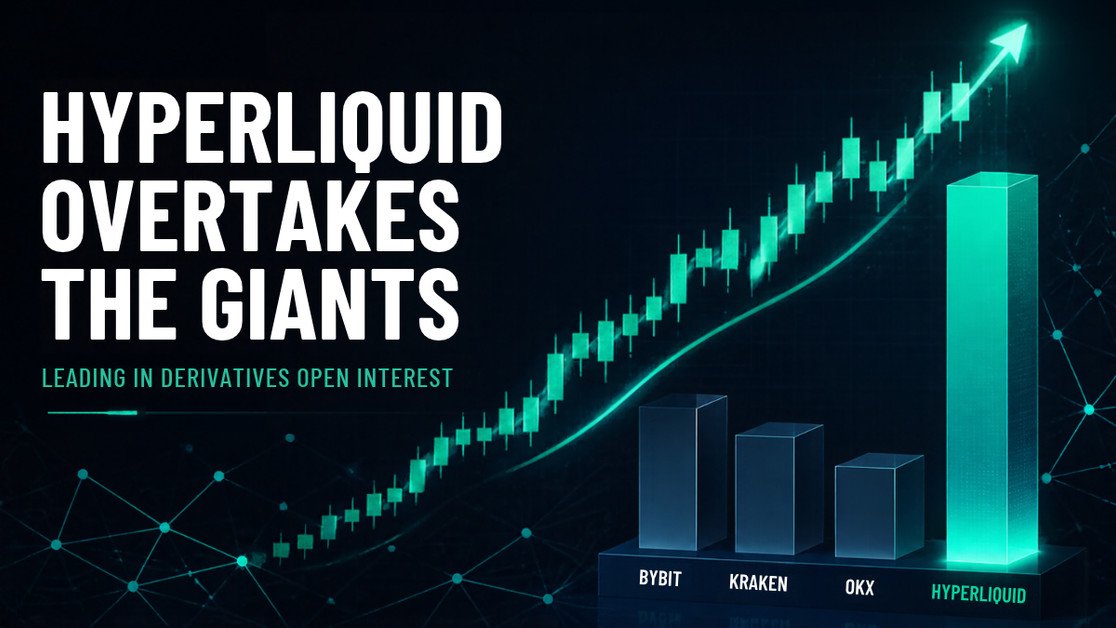
For years, the crypto derivatives market belonged to the big centralised exchanges. Traders went to Binance, Bybit, OKX and Kraken because that was where the liquidity was — and liquidity, in trading, is everything. This week, the third-quarter numbers showed that one of those certainties has quietly broken. Hyperliquid, a decentralised exchange that runs on code rather than a company, ended September with more open derivatives positions than Bybit, Kraken and OKX.
It is the clearest sign yet that the centre of gravity in crypto trading is shifting — and it arrived on one of the worst weeks of the year for prices.
The numbers behind the upset
According to a quarterly report from the Hyperliquid Research Collective, cited by The Block, Hyperliquid closed the third quarter with a record $16.8 billion in open interest — the value of outstanding positions in its perpetual futures contracts. That is up nearly 80% from $9.31 billion at the end of June. Open interest peaked even higher during the quarter, hitting a record $18.1 billion on 22 September.
The exchange’s share of open interest across Hyperliquid and eight major exchanges climbed to 11.7%, up from 9.6% three months earlier. It moved past Kraken and Bybit on 12 August, then overtook OKX on 17 September. The rest of the business grew with it: third-quarter revenue rose 22% to $191 million, matched trading volume reached $730.6 billion, and average daily traders hit a record 65,161, up 20% on the quarter. Trading in stock-linked perpetual contracts — bets on traditional assets such as equities, indices and commodities — surged 161%.
Perspective matters, though. Binance remains far ahead: Hyperliquid’s quarter-end open interest was about 27% of Binance’s, and roughly 93% of Bitget’s. And the headline depends on how you measure it. Separate research from TokenInsight, which uses average open-interest share across the quarter rather than the quarter-end snapshot, still places Bybit above Hyperliquid, at 12.55% against 10.00%, with Binance leading at 32.04%. Both measures agree on the direction of travel; they disagree on exactly when the line was crossed. Either way, a decentralised platform built in the last few years is now trading blows with exchanges that have dominated the market for a decade.
What open interest actually tells you
Open interest is often confused with trading volume, but the two measure different things. Volume counts how much changed hands; open interest counts how much is still outstanding — the total value of positions that traders have opened and not yet closed. When it rises, it means new money is entering the market and traders are putting on bigger bets. When it falls, positions are being closed, willingly or by force.
That makes it a useful gauge of where traders actually want to be. Volume can be inflated by the same money changing hands many times; open interest cannot. Hyperliquid’s jump, then, is not just a busy quarter — it is a growing pile of traders choosing to keep their positions on a decentralised venue rather than a centralised one.
A record week in a falling market
The timing is striking. The same week these numbers landed, the wider market was falling apart. Bitcoin traded around $68,300 on Saturday, down 4.4% in 24 hours and below $70,000 for the first time since mid-August, after touching an intraday low near $66,915. Ethereum fell to about $1,930, Solana to roughly $78, and the total crypto market cap slipped to around $2.33 trillion. More than $1.29 billion in leveraged positions was liquidated in a single day, with 164,145 traders wiped out — the largest single liquidation, worth $20.15 million, happened on Hyperliquid itself. The Crypto Fear & Greed Index sank to 13, its lowest reading since July.
And yet Hyperliquid’s own token, HYPE, rose about 7% on the day. Traders, it seems, are separating the market’s direction from the venue’s momentum: even as prices fall, the platform where the bets are placed keeps gaining ground.
The other side of the trust question
There is a second story this week that explains why traders might be drifting toward venues they can verify for themselves. Unocoin, one of India’s oldest crypto exchanges, has suspended all services after a security incident — and its dispute with its custody provider, BitGo, has turned into a public argument about who holds the keys.
Unocoin says it detected unauthorised activity on 6 November and asked BitGo and Fireblocks to freeze its enterprise accounts within minutes of each other. Further unauthorised activity on 9 November pushed it to shut down every service and rebuild its servers from scratch, a job it expects to take four to five working days. Then, on 12 November, it found outgoing transactions from one of its Ethereum addresses in its BitGo wallet infrastructure — transactions it could not trace, because its accounts were frozen and it could not log in.
BitGo’s answer, given on 13 November, was blunt: its systems were not breached, and the transfers were signed using Unocoin’s own user and backup keys under a two-of-three signing arrangement, broadcast directly on-chain without BitGo’s participation. “BitGo’s key was never used,” the company said. Unocoin has acknowledged the transfers were signed and broadcast outside BitGo’s platform, and says more than 90% of customer funds are held in cold storage, offline. It continues to tell users no funds have been lost.
Nobody has yet established the root cause, and the investigation continues. But the episode is a reminder of the fault line running through crypto custody: in a centralised setup, safety depends on who holds which keys and whether everyone agrees on what happened. On a decentralised exchange, every position and every trade is visible on-chain by design. That transparency is a large part of what Hyperliquid is selling — and this week, buyers kept buying it.
What to watch next
The question now is whether Hyperliquid can hold the lead it has taken. The fourth quarter will test it: open interest is quick to build and quick to leave, and a prolonged sell-off could drain positions across every venue. Watch whether its share of open interest keeps climbing when the market turns, whether its stock-linked contracts keep growing, and whether rival decentralised platforms follow it up the rankings.
Also watch Unocoin’s reopening. The exchange has given no fixed date, only that withdrawals will resume once services are restored and security checks are complete.
For now, the scoreboard says something that would have sounded unlikely two years ago: the biggest derivatives venues in crypto include one that has no headquarters, no order book hidden behind a login screen, and no customer support desk. It just has code — and, as of September, more open positions than three of the industry’s biggest names.
This post is for information only and is not financial advice. Figures are as reported by The Block, FXStreet, Crypto Briefing, TokenInsight, KuCoin, CoinGabbar and Unchained on 13–14 November 2026. Open-interest rankings depend on the measurement used, as noted in the article. Cryptocurrency markets are volatile — do your own research before making investment decisions.